Deductibles, explained

How Do Hurricane and Roof Deductibles Work in Florida, and What Will I Pay?

You pay the deductible, and insurance pays the rest of a covered loss. For hurricane damage in Florida it's often a percentage of your dwelling limit, like 2%, applied once per calendar year. Some policies add a separate roof deductible. If the damage costs less than the deductible, the claim pays nothing. Your declarations page shows the dollar amounts.

Most people don't look at their deductible until shingles are already in the yard. Below: where Florida law puts the numbers on your policy, how the separate roof deductible works, and what a storm claim actually pays, with example numbers worked out.

Licensed & InsuredFlorida CCC1331076
4.7 stars65+ Google reviews
10 yearsFlorida-licensed
2,000+Roofs completed
Two deductibles

What's the difference between a hurricane deductible and a regular deductible?

A hurricane deductible applies only to hurricane losses, is often a percentage of your dwelling limit, and applies once per calendar year. Other covered losses, like wind damage from a storm that isn't a hurricane, fall under your regular deductible for all other perils.

Florida Statutes section 627.701(3)(a) requires insurers to offer hurricane deductible choices of $500, or 2%, 5% or 10% of the policy's dwelling limit, with some exceptions on higher dwelling limits. The percentage comes from your dwelling limit, not from the size of the damage. On a $350,000 dwelling limit, 2% is $7,000, 5% is $17,500 and 10% is $35,000. That's the share of hurricane damage you cover before the policy pays anything.

Under section 627.701(5)(a)1., the hurricane deductible "shall apply on an annual basis to all covered hurricane losses that occur during the calendar year," across policies from the same insurer or insurer group. You don't owe a full new one for every storm.

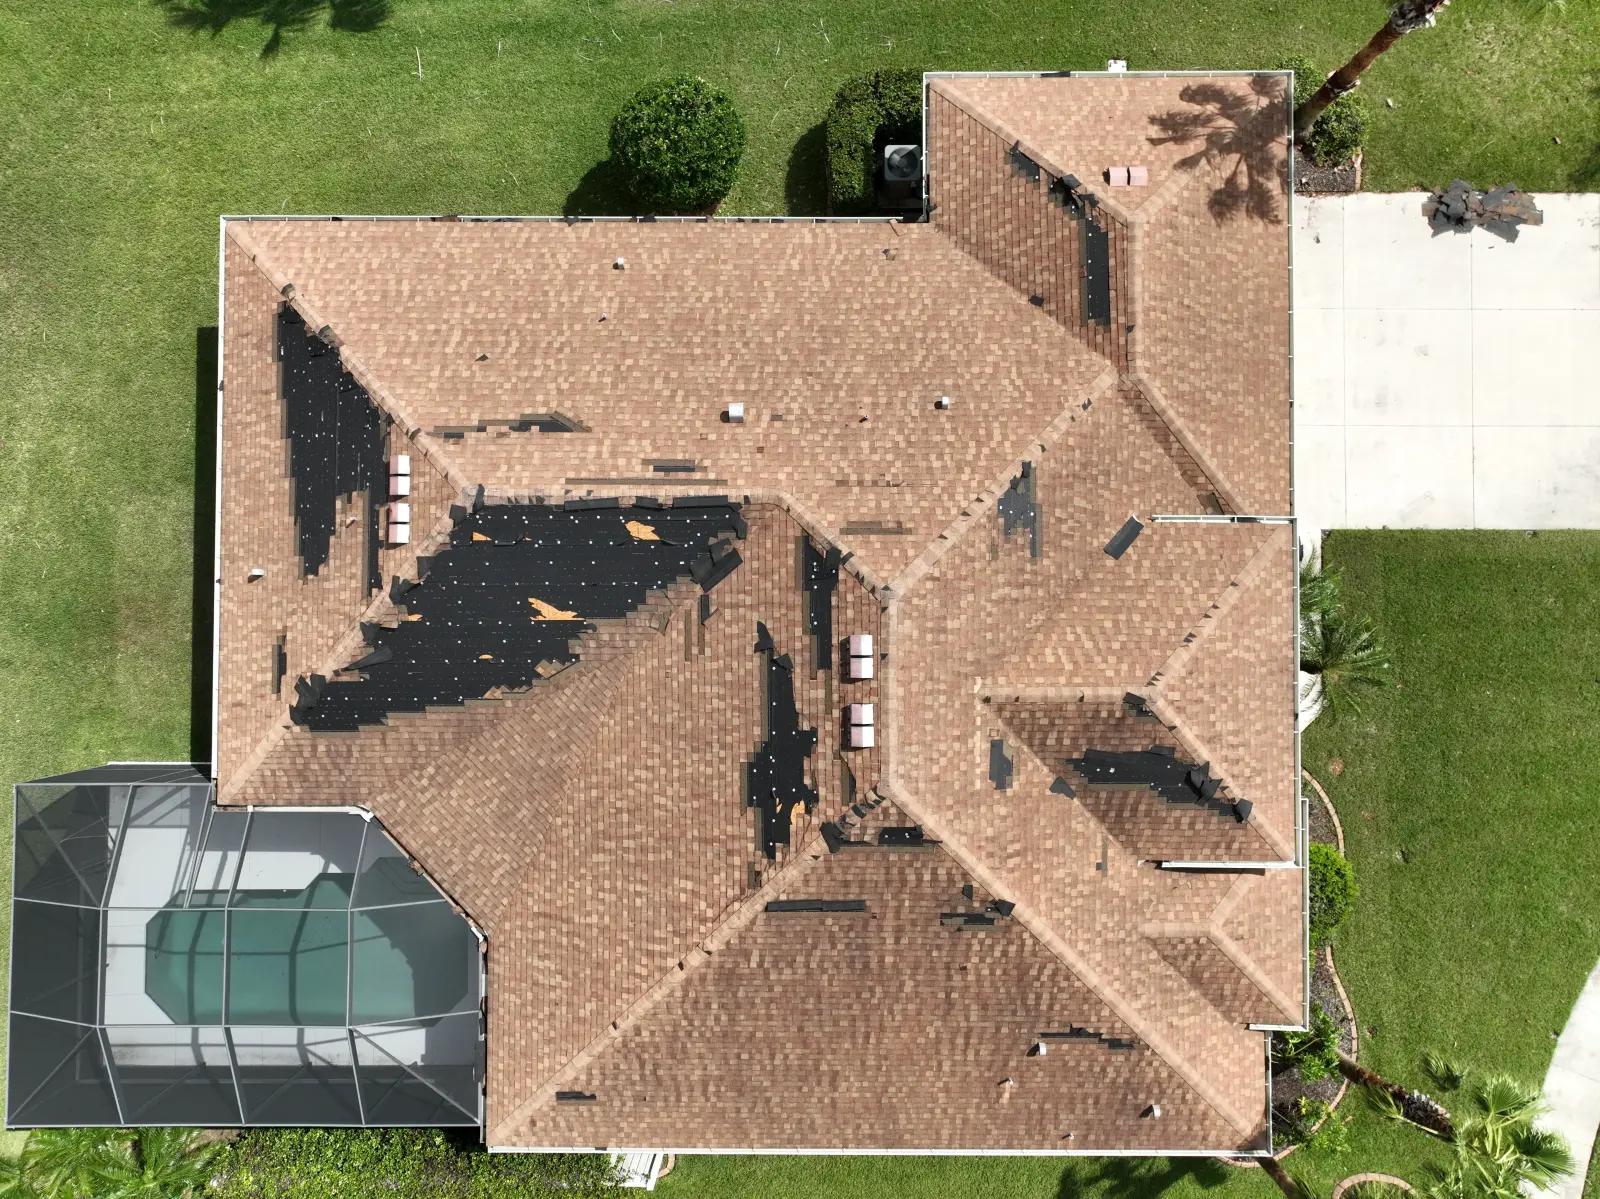
Storm-damaged tile roof on the Florida Gulf Coast with cracked and displaced tiles, October 2024
Storm-damaged tile roof, Florida Gulf Coast, October 2024, with cracked and displaced tiles.
Your paperwork

Where do I find my hurricane and roof deductibles?

On your declarations page. Florida law requires your insurer to show the hurricane deductible there as an actual dollar amount, not just a percentage.

  1. Look for the bold warning

    Section 627.701(4)(a) requires the face of the policy to carry this statement in bold type no smaller than 18 points: "THIS POLICY CONTAINS A SEPARATE DEDUCTIBLE FOR HURRICANE LOSSES, WHICH MAY RESULT IN HIGH OUT-OF-POCKET EXPENSES TO YOU."

  2. Read the dollar amount

    Under section 627.701(4)(b), the insurer must figure the actual dollar value of your hurricane deductible and display it prominently on the declarations page when the policy is issued.

  3. Check the page right behind it

    If your policy has a separate roof deductible, section 627.701(4)(e) puts a bold notice on the page immediately behind the declarations page. It begins "YOU ARE ELECTING TO PURCHASE COVERAGE ON YOUR HOME WHICH CONTAINS A SEPARATE DEDUCTIBLE FOR ROOF LOSSES." Its dollar amount also goes on the declarations page or renewal notice.

  4. Recheck at every renewal

    At renewal, the hurricane dollar amount appears on the renewal declarations page or premium renewal notice. If your dwelling limit went up, a percentage deductible went up with it. Read any notice of change, too: that's how a roof deductible can be added.

Roof deductible

What is a separate roof deductible in Florida?

It's an optional deductible for certain roof losses, allowed under Florida Statutes section 627.701(10) since 2022 (chapter 2022-268, Laws of Florida). Insurers don't have to include one, and the law sets firm limits when they do.

It has a cap

It can't be more than the lesser of 2% of your Coverage A limit (your dwelling coverage) or 50% of the cost to replace the roof. Whichever number is lower is the ceiling.

It comes with a discount

The law requires "an actuarially sound credit or premium discount" for the roof deductible. Ask your agent what that credit is worth on your premium.

Replacement cost claims only

It applies only to a claim adjusted on a replacement cost basis. Under section 627.7011(3)(a), the insurer may limit the roof payment to actual cash value until it gets reasonable proof you paid the roof deductible, so keep your receipt.

Some roof losses are left out

It does not apply to roof damage from a hurricane, a tree fall or other hazard that punctures the roof deck, a total loss under Florida's valued policy law, or a roof loss that needs repair of less than 50% of the roof.

One deductible per loss

When the roof deductible applies, no other deductible in the policy can be applied to that loss or to other damage from the same covered peril. It never stacks on your regular deductible.

You can say no

On a new policy it must be offered with the ability to opt out. At renewal, an insurer can add it with a notice of change in policy terms but must offer the same opt-out. To reject it, you sign a form approved by the state's Office of Insurance Regulation.

The math

What will I actually pay on a roof claim?

Your deductible comes off the covered damage first. If the damage is less than the deductible, the claim pays nothing. If it's more, the policy pays the difference, subject to the rest of your policy's terms.

Here's the math on one house with made-up numbers. Your own deductible and damage will differ.

Example, not a quote: a home with a $350,000 dwelling limit
What happenedDeductible that appliesCovered damageYou payPolicy pays
Hurricane, minor roof damage2% hurricane deductible: $7,000$5,000$5,000$0
Hurricane, major roof damage2% hurricane deductible: $7,000$18,000$7,000Up to $11,000
Windstorm that isn't a hurricaneAll-other-perils deductible: $2,500$4,000$2,500$1,500

The third row is the one people miss: not every wind claim is a hurricane claim. "Policy pays" means before anything else in your policy comes into play. If your insurer pays the roof at actual cash value first and holds back depreciation, the first check will be smaller, and our plain-English breakdown of ACV and RCV explains that holdback.

Roof deductible math, same house

The cap is the lesser of two numbers. 2% of the $350,000 Coverage A limit is $7,000. If the roof would cost $10,000 to replace, half of that is $5,000, so the roof deductible can't be more than $5,000. If it would cost $20,000, half is $10,000, and the cap is the $7,000 from the 2% side. Even then, it only applies to a replacement cost claim on a roof loss that needs at least half the roof repaired and didn't come from a hurricane or a tree punching through the deck.

Two storms, one year

What happens if a second hurricane hits in the same year?

You don't start over with a full new hurricane deductible. For the next hurricane, your insurer may apply whichever is greater: what's left of your hurricane deductible, or your all-other-perils deductible.

That rule is section 627.701(5)(a)3. Say your hurricane deductible is $7,000 and an August hurricane does $5,000 of covered damage. You pay all $5,000, and if that loss counts toward your deductible, $2,000 of it is left. When an October hurricane hits, your insurer may apply the greater of that $2,000 or your $2,500 all-other-perils deductible, so $2,500. If the first storm had done only $1,000 of damage, the $6,000 left over would be the greater number.

The catch is proof. The same subsection lets insurers require you to report hurricane losses below the deductible, or to keep receipts. So even when a small hurricane repair isn't worth a claim, keep these, and ask your agent whether they want the loss reported:

  • The written estimate and the paid invoice
  • Dated photos of the damage and the finished work
  • A note of when you told your insurer, if you did
Claim or skip it

Is it worth filing a claim if the repair costs less than my deductible?

Not for the payout. If the repair costs less than your deductible, the claim pays nothing. Get a free written estimate first and compare it to the dollar amount on your declarations page.

Our free roof inspection is drone-assisted, comes with a written photo report you keep, and has no trip or diagnostic fee. Every estimate we write is line by line, so you can hold it up against your deductible before you decide whether to file. For what moves the price of a repair, see how Florida roof repair costs add up. You can also text photos of the damage to (941) 345-0072.

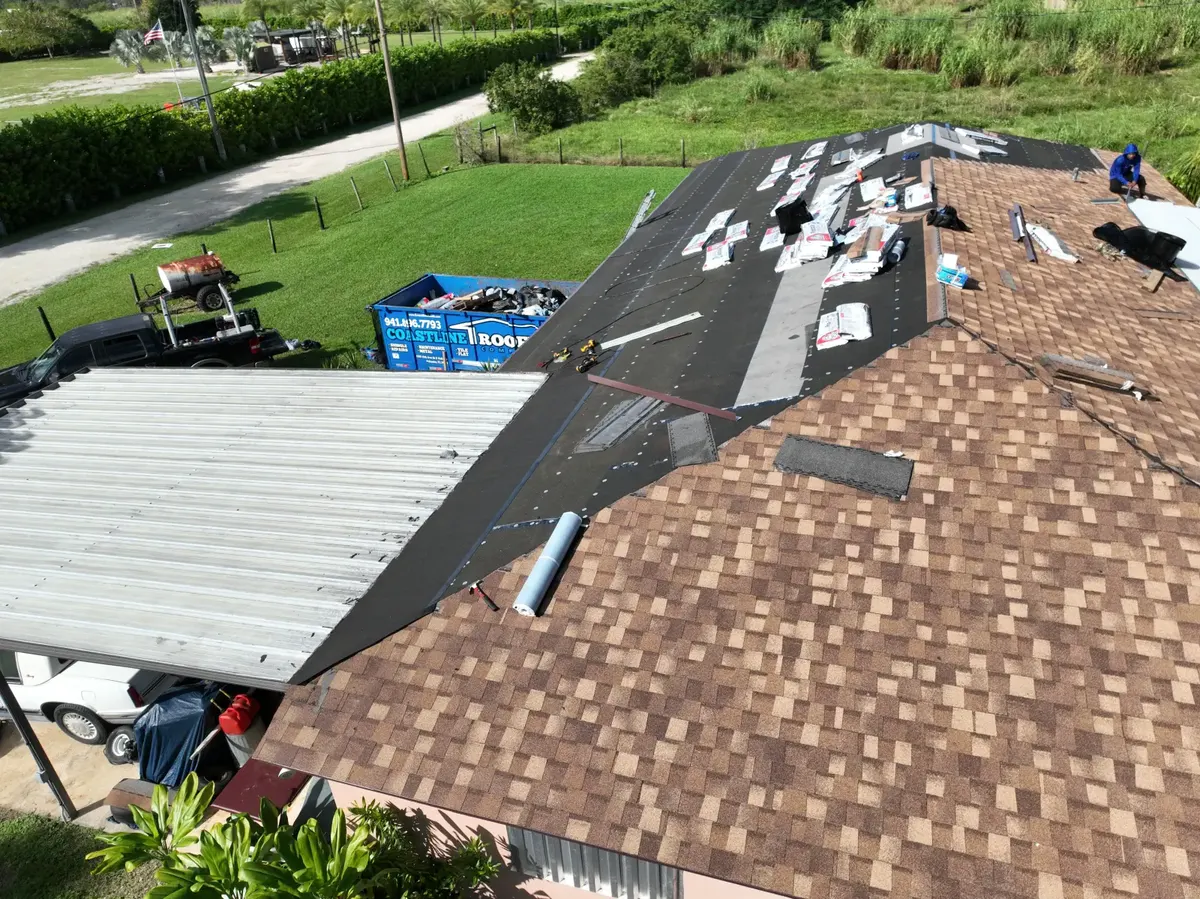
Shingle roof replacement in progress, November 2024
Shingle replacement in progress, November 2024.

If the damage turns out bigger than it looked, watch the clock. Under section 627.70132, notice of a new or reopened claim must be given to your insurer within 1 year after the date of loss, and a supplemental claim within 18 months. For a hurricane, the date of loss is the date the hurricane made landfall.

Know the law

Can a roofer pay or waive my deductible?

No. Florida law bars contractors from offering to waive your deductible in exchange for a roof inspection or a roof claim. Knowingly paying, waiving or rebating a deductible with intent to defraud is a felony.

Section 489.147(2)(b) says a contractor may not offer "a rebate, gift, gift card, cash, coupon, waiver of any insurance deductible, or any other thing of value" in exchange for inspecting your roof or for you making a claim for roof damage. Under subsection (3), a contractor can be fined up to $10,000 for each violation. Section 817.234(7)(d) goes further: a contractor who knowingly or willfully pays, waives or rebates all or part of an insurance deductible, with intent to injure, defraud or deceive, commits a third-degree felony.

So "we'll take care of your deductible" is a warning sign, not a favor. Walk away, and read our page on spotting storm-chaser roofing scams before you sign anything.

What we are, and what we aren't

Coastline is a roofing contractor, not a lawyer, public adjuster or insurance agent. We document the damage with photos and work alongside your adjuster. For advice on your own situation, read your policy and ask your agent or another licensed professional.

Reviews

Homeowners on upfront estimates and quick answers

★★★★★
"I highly recommend Coastline Roofing to anyone looking for reliable, high-quality roofing services. Extremely professional and punctual. They provided a detailed estimate upfront with no hidden costs, and the quality of their workmanship is outstanding."
John L.Roofing customer, Florida Gulf Coast
★★★★★
"I really lucked out. My inspection and resolution was performed all in the same day. I'm grateful."
Sekina F.Same-day inspection and repair, Florida Gulf Coast
★★★★★
"High quality work and fast turn around times. Was flexible to my schedule and my unique requests."
Troy P.Roofing customer, Florida Gulf Coast
FAQ

More deductible questions

Can I get a $500 hurricane deductible?

Maybe. Insurers must offer $500 as one of the choices, but under section 627.701(3)(d)1. they don't have to offer it on dwelling limits of $250,000 or more. On a larger home, your choices may all be percentages. Ask your agent what each option does to your premium.

Do I pay both a hurricane deductible and a roof deductible?

Not on the same loss. The roof deductible doesn't apply to roof damage from a hurricane, so the hurricane deductible handles that. And when the roof deductible does apply, the law says no other deductible in the policy can be applied to that loss.

Does a separate roof deductible depend on how old my roof is?

No. Section 627.701(10) doesn't mention roof age. The cap is tied to your Coverage A limit and the cost to replace the roof. If your insurer is raising roof age, that's a separate issue from the roof deductible.

How do I pay my deductible on a roof job?

It's the part of the bill you cover yourself. Keep proof you paid it, especially with a roof deductible, since your insurer may hold the roof payment at actual cash value until it sees that proof. Section 627.7011(3)(a) lists a canceled check, money order receipt, credit card statement, or a signed installment or financing contract as reasonable proof. We take check, credit card, Zelle, Venmo and cash, and offer financing through Ygrene and Synchrony Bank for qualified homeowners.

Get a written estimate to hold up against your deductible

Book a free, drone-assisted roof inspection with a written photo report you keep. No trip fee, no diagnostic fee, and a line-by-line estimate so you can decide about a claim with real numbers.

Call Text